
News & Insights
The lake, it is said, never gives up her dead, when the skies of November turn gloomy. Thus said Gordon Lightfoot in his epic ballad “The Wreck of the Edmund Fitzgerald,” about that ship’s tragic encounter with the November gales of Lake Superior, fifty-one years ago. The turbulence of late fall in the Great Lakes region is caused by the clashing of cold temperatures arriving from the north and the lingering summer air that keeps water temperatures relatively high through the early parts of the season. Miles and miles of open water create the conditions for currents to gather momentum and turn into monster waves. The gales of November, legends told since time immemorial by those who live near its waters, have claimed many ships and many lives.
Turbulence Hits Hard
Financial markets have been dealing with their own version of the gales of November for several weeks, and the turbulence ramped up in intensity this week. The S&P 500, as of its Thursday close, was down 8.2 percent from its last record high, set on October 6.
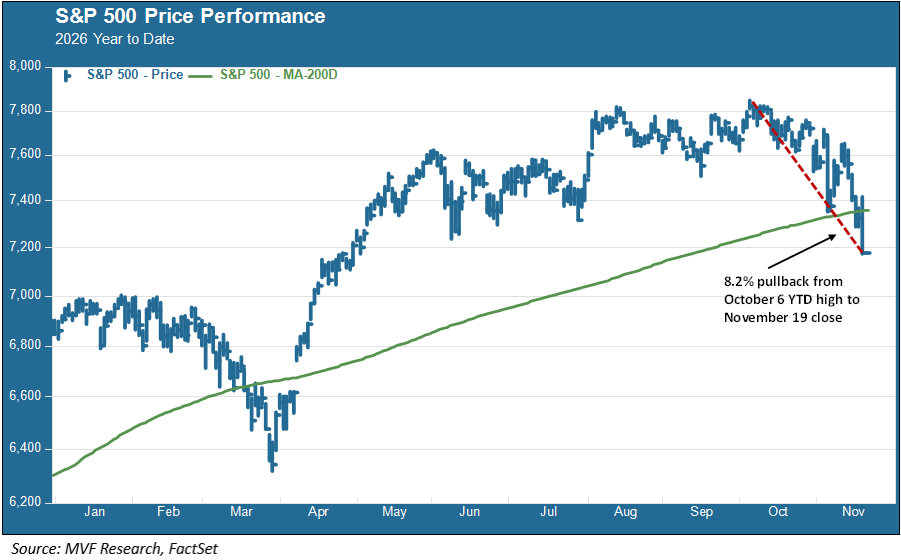
The volatility was particularly nasty on Thursday, with a confluence of events swirling around the market discourse. Just one day after receiving another blockbuster earnings report from Nvidia, and trying to balance the positive news from the numbers with the ongoing fallout from founder Jensen Huang’s departure, the initial public offering of AI frontier model leader Anthropic hit the tape. At first it looked like Anthropic was going to inject some badly-needed animal spirits into market sentiment, with the new shares popping up nearly 40 percent in early trading. But the good vibes fizzled out in due course and prices broadly went south. The S&P 500 breached a key technical indicator, the 200-day moving average, for a third consecutive day, which has potential implications for near-term sentiment.
Technicals and Fundamentals
Shares in AI-related companies, of course, are getting the worst of the witch of November (a colorful expression the Chippewa tribes of the Great Lakes region have used to describe the seasonal phenomenon). Many of the extreme intraday movements have come from institutions like hedge funds with short-term trading strategies based on quantitative triggers. There are three fundamental concerns underlying the technical selling. The first came in the aftermath of the midterm elections earlier this month, when the resounding Democratic victories all over the country called into question the future of what, under the current administration, has been a very lax approach to regulating AI. Opposition to data center development was a huge issue in the election, and while comments from incoming Democratic leaders, notably including Texas governor-elect Gina Hinojosa, have been relatively moderate in tone, the potential for more regulatory restraints is causing a repricing of assumptions.
The second concern, clearly, is l’affaire Huang. Nvidia’s sales and earnings results earlier this week clearly demonstrated that the company has a locked-in growth and profit margin model that will carry through at least to the end of the decade. But during the earnings call interim CEO Colette Kress was cooler on the continuation of Nvidia as the “AI central bank” that was a key plank of the Huang model. That implies capital constraints, in addition to regulatory constraints, and puts more weight on that repricing exercise.
Finally, there has been a great deal of “what the heck is going on?” feeling out there, and not just from the financial markets chattering class. The outages that have taken place across everything from the airline system to big banks to Apple software in the past week are unnerving many people. There is a reasonable explanation for what is going on – the AI platforms are able to detect flaws and vulnerabilities in legacy software systems at a rate never seen before. Companies are rushing to patch up their bugs with upgrades, and sometimes (as with last Friday’s shutdown of the airline system) things go south during the upgrade process. But that explanation leads to more questions.
All of this – the regulatory implications of a power shift in Washington and governors’ mansions, the end of the Central Bank of Nvidia, the software chaos – is creating turbulence not unlike the warm air – cold air clashes over the Great Lakes. The potential good news is that addressing these issues in the open can lead to resolutions and act as a clearing event that will eventually settle down and calm nerves. A more transparent – and better regulated – AI industry should produce longer-term benefits. Meanwhile, there is likely to be a bit more choppiness until we get clear through the gales of November.