
News & Insights
Last week in this space we took a look back at the dot-com crash of 2000-02 and debated what might be different, and what might not be different, this time with the troubled trajectory of the AI trade. As much as we might have liked to write about something else this week, events once again drag us back to the same story. While there is a bit of a bounce in shares this morning, the market has only been open for seven minutes as these words get typed, so we are not making any predictions as to where things end up when this trading week comes to its merciful end a few hours hence.
Playing Through the Election
There is a conventional wisdom narrative going around that the seismic drop in US stock indexes on Thursday was a reaction to the “blue tsunami,” or whatever oceanographic metaphor you choose to use, that decisively flipped both the House of Representatives and the Senate back to Democratic control (that control, of course, does not formally take place until January). The argument here is that the party which campaigned on opposition to data centers while calling for more regulation of the AI sector is poised to call into question the viability of all those hundreds of billions of dollars being spent on AI build-out. There is probably some element of truth to that argument, but it is only one factor among the many we talked about last week that have been spooking investors for the better part of the past month.
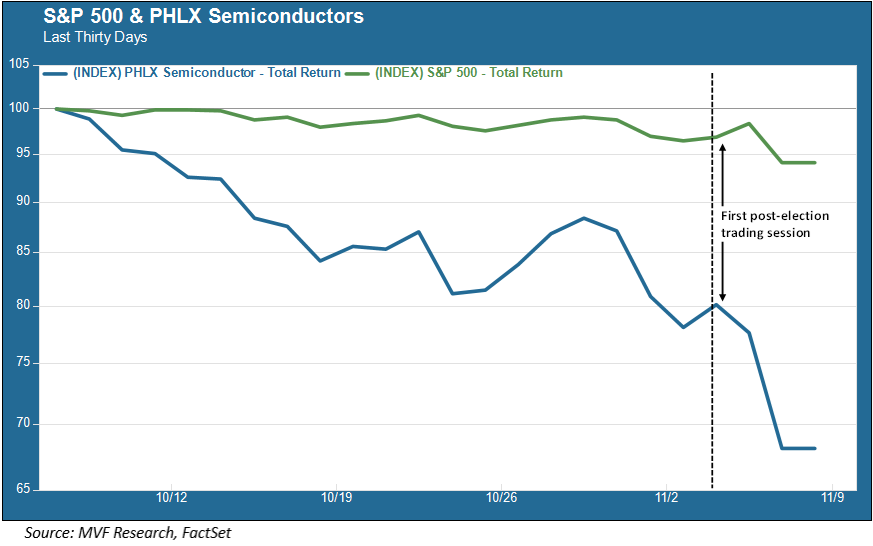
Indeed, the broader stock market, represented in the above chart by the S&P 500, had a nice rally the day after the election, closing up 1.6 percent on Wednesday. But the AI trade, depicted here by the Philadelphia Semiconductor index, basically played through the election and kept on the losing ways that, barring a few days of a relief rally towards the end of last month, have been the general trend since early October. What the midterm results probably did was to serve as a hair-trigger catalyst for automated, scattershot institutional selling by hedge funds and other short-term traders
Caffeine Jolt for the VIX
Was the selling justified? Not on the basis of any substantial news. It is far too soon to tell what impact the new configuration of Congress will have, in a practical sense, on the continued infrastructure build-out. The governor-elect of Texas, Gina Hinojosa, commented yesterday that the issue is not opposition per se to data centers, but ensuring that the process take into account the interests of stakeholders beyond simply those of the hyperscalers, neocloud providers etc. doing the building and servicing. And yes, regulation of the industry is going to happen sooner or later, regardless of who is in power in Washington, just like with every other major technology paradigm from the canals and railroads through electricity, the internal combustion engine and telecommunications.
In the near term, we expect the market to do what it often does when working its way through a sea of unknown outcomes – and that means more volatility. The CBOE VIX index, the market’s so-called fear gauge, started to rouse itself from a very calm late summer snooze as the AI trade started to turn south last month. Yesterday it spiked up to levels not seen since the outbreak of the war in the Middle East earlier this year.
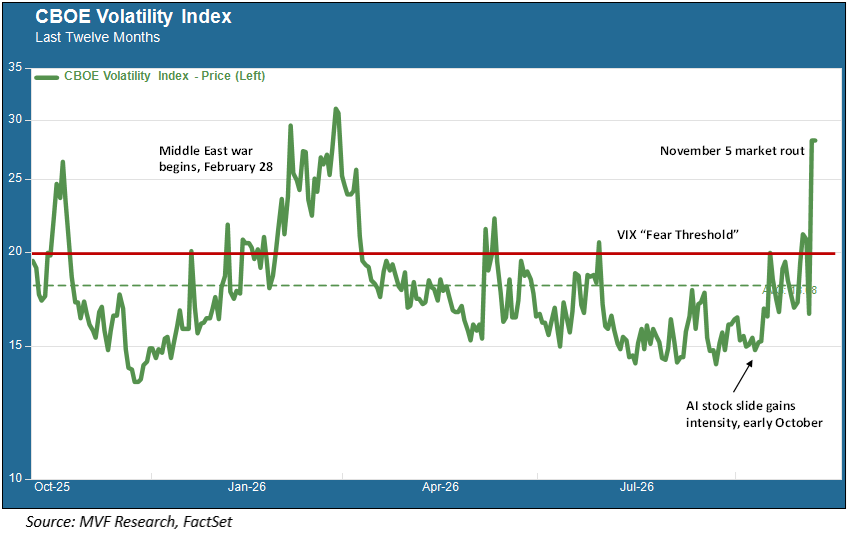
We expect more of this bumpiness going forward, although the impact of AI-related edginess on the broader market may be offset somewhat by the usually supportive forces that come into play as the holiday shopping season gets into full swing. As for the fate of the AI trade, we will make one closing observation. The Bureau of Economic Analysis released its report on productivity for the third quarter yesterday, and that came in at a very healthy 3.6 percent (annualized), well above economists’ expectations. Productivity over the last sixteen months or so has been trending generally higher than its baseline averages during the 2010s. While it is too early to confidently ascribe that improvement to the growing presence of AI in the workplace, there is a plausible connection. Productivity is what creates long-term, sustainable growth – something that any sensible politician from whatever side of the aisle should want. This will bear continued scrutiny as we look ahead to the year to come.